Local Guide
What Locals Wish They Knew Before Moving to Tampa Bay
Moving to Tampa Bay? Locals wish they'd known about flood zones, insurance, property taxes, traffic, schools, water rules, and the real monthly numbers.
By Holden Kellerhals, NMLS #2646551Pinellas County, Florida
Quick Answer
What do I need to know before moving to Tampa Bay?
Check the exact address before you fall for the house: flood zone, evacuation zone, insurance quotes, tax estimate, school assignment, and rush-hour commute. In Tampa Bay those six details change your monthly cost more than the list price does.
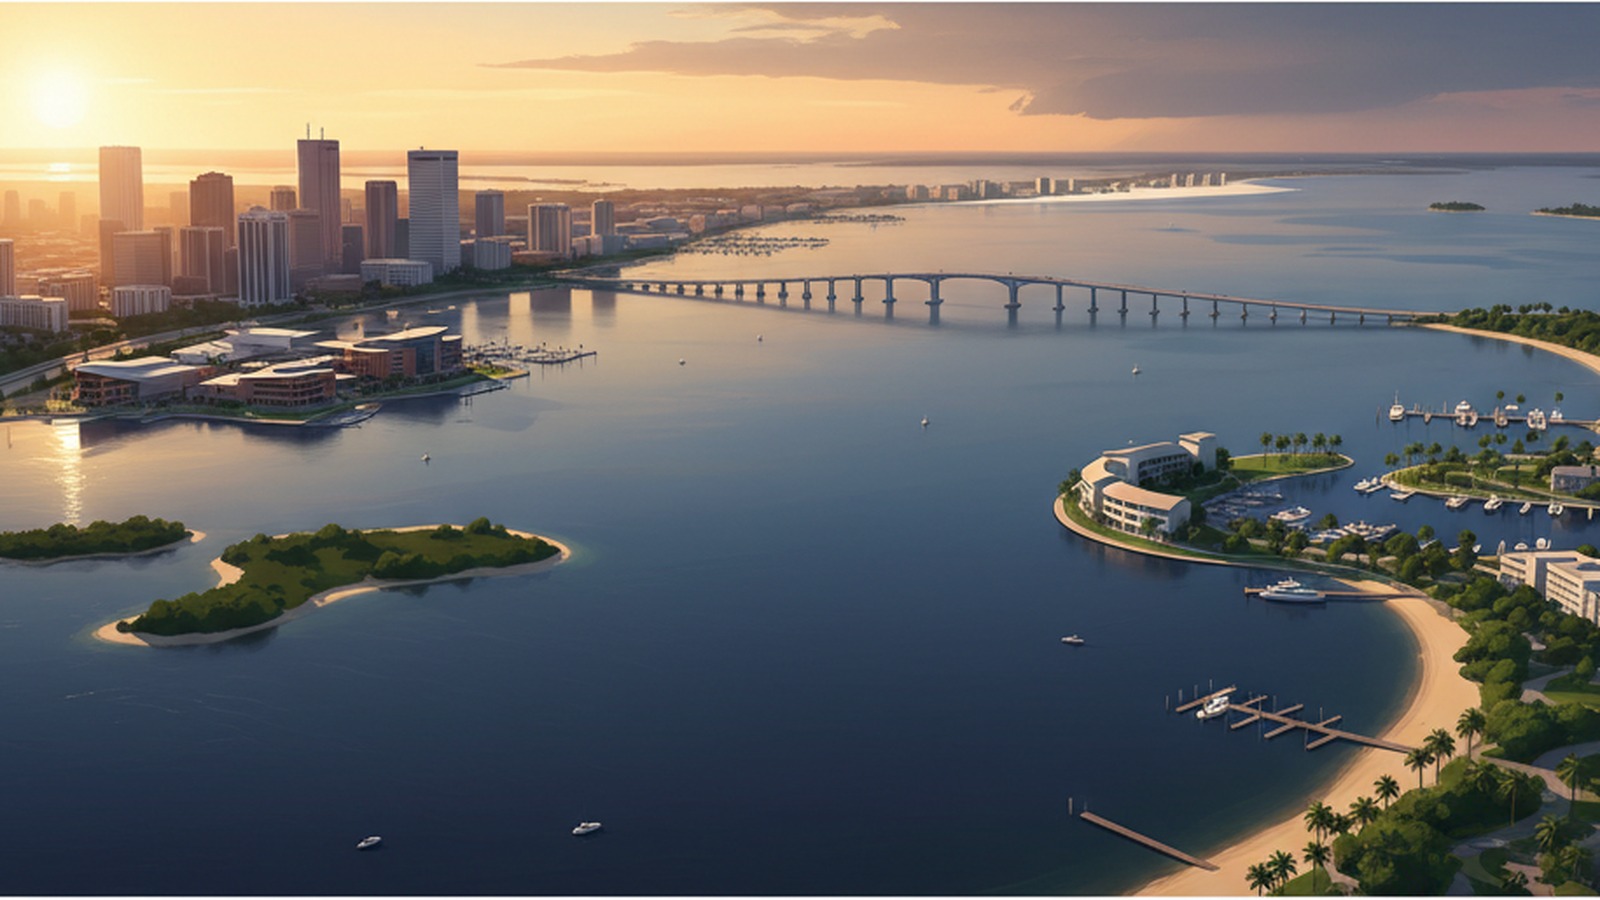
If you're making a list of things to know before moving to Tampa, start with the unglamorous stuff. Most people compare list prices first. Then insurance, flood zones, taxes, traffic, and lawn rules surprise them.
Tampa Bay is not one city. If you are still deciding whether to move, start with the county-level basics. Hillsborough, Pinellas, and Pasco have different school districts, transit, utilities, tax authorities, and flood risks. Two houses 15 minutes apart can carry very different monthly costs. Before you fall for a kitchen, check the flood zone, evacuation zone, insurance quotes, tax estimate, school assignment, and rush-hour commute. Research is current as of October 19, 2026.
1. Tampa Bay is three counties wearing one name
Hillsborough includes Tampa, Plant City, Temple Terrace, and unincorporated land. Pinellas holds St. Petersburg, Clearwater, Largo, Dunedin, and the beaches. Pasco runs from New Port Richey east to Wesley Chapel and Land O' Lakes.
Each county has its own appraiser, tax collector, school district, and emergency office. Hillsborough uses HART; Pinellas uses PSTA.
Hillsborough
- Core cities and communities: Tampa, Plant City, Temple Terrace
- School district: Hillsborough County Public Schools
- Main regional links: I-275 and the Howard Frankland Bridge, Gandy Bridge, I-4
Pinellas
- Core cities and communities: St. Petersburg, Clearwater, Largo, Dunedin
- School district: Pinellas County Schools
- Main regional links: Howard Frankland Bridge, Gandy Bridge, Sunshine Skyway
Pasco
- Core cities and communities: New Port Richey, Wesley Chapel, Land O' Lakes, Zephyrhills
- School district: Pasco County Schools
- Main regional links: I-75, SR 54, SR 56
The differences between Tampa, St. Petersburg, and Clearwater deserve their own comparison before you commit.
2. Your flood zone and evacuation zone are different
Two maps confuse almost every newcomer: FEMA's flood map and the county evacuation map.
Your flood zone is about your property's risk of flooding. It drives flood insurance and building rules. Your evacuation zone is about storm surge. It tells you when officials may order you to leave. The City of Tampa puts it plainly: a home can be outside an evacuation zone and still be in a high-risk flood zone, or the reverse. Hillsborough's zones run A through E; Zone A is generally first to go.
Check both at the exact address using FEMA's Flood Map Service Center and your county's evacuation lookup. In Pinellas County, mobile and manufactured homes must always evacuate because of wind risk. If you are building a timeline, put these checks in order before you start touring homes.
If you're buying, Florida law requires a flood disclosure at or before contract. It covers known flooding, flood insurance claims, and FEMA assistance (Fla. Stat. § 689.302). Read it, then get your own quote. NFIP policies generally take effect 30 days after purchase, except when coverage is bought with a mortgage.
3. Insurance is a budget line, not a closing afterthought
Insurance is a monthly cost, an underwriting decision, and sometimes a deal-breaker.
Start with the deductible. Florida insurers generally must offer hurricane deductibles of $500, 2%, 5%, or 10% of the dwelling limit (Florida DFS). A 2% deductible on a $400,000 dwelling limit is $8,000 before the policy pays for hurricane damage. It applies once per calendar year with the same insurer or group, separate from your all-other-perils deductible.
A standard homeowners policy does not cover flood. You need a separate flood policy, from NFIP or a private insurer. Ask about wind mitigation credits, roof age, and inspections the carrier requires.
For a condo, ask for the master policy, deductible, milestone inspection report, structural integrity reserve study, and current budget. Florida requires milestone inspections for residential condo buildings three or more habitable stories at 30 years, or 25 if the local enforcement agency requires it (DBPR). Reserves and special assessments can change your HOA payment; a low list price can hide a thin reserve account.
4. Property taxes are local, and the rules may be changing
Property taxes are local, and the bill is more than a millage rate.
Your bill can include county, city, school, water, and special-district levies, plus non-ad valorem charges like trash, stormwater, and CDD fees. Homestead does not reduce those charges.
If it is your primary residence, file for homestead. In Hillsborough, homestead exempts up to $50,000: the first $25,000 is fully exempt; the second applies between $50,000 and $75,000 but not to school taxes (HCPA). Save Our Homes caps annual assessed-value increases at the lower of 3% or CPI. File by March 1; you must own the property and establish residency by January 1 of the claim year. Portability applies within Florida; out-of-state owners have no benefit to port.
Taxes are paid in arrears. The 2026 bill reflects the 2026 tax year and is discounted 4% in November, 3% in December, 2% in January, and 1% in February if paid early (Hillsborough Tax Collector).
Amendment 3 is on the November 3, 2026 ballot. It would raise the non-school homestead exemption from $50,000 to $150,000 in 2027 and $250,000 in 2028, cut the non-homestead assessment cap from 10% to 5%, and require 60% approval. It would not change 2026 bills. The summary also notes a five-year residency requirement for the higher exemption (Hillsborough Tax Collector). Passage is not guaranteed; don't budget on it.
5. The rainy season is a lifestyle, not just weather
The National Weather Service defines the rainy season for west-central Florida as May 25 through October 10. Dew points climb above 70°F, lows stay in the 70s to around 80°, highs run from the upper 80s to mid 90s, and afternoon thunderstorms become routine (NWS Tampa Bay). Check drainage, roof age, windows, HVAC, attic ventilation, and humidity in an empty house.
Hurricane season runs June 1 through November 30 (NOAA/NHC). Storm surge and flooding cause much of the damage, which is why evacuation zones are based on surge. Know your zone and route. "I'm not in a flood zone" is not the same as "I don't need to evacuate."
Red tide is episodic. Karenia brevis blooms can cause respiratory irritation, fish kills, and beach closures. Check FWC's status before a beach day, especially if someone has asthma.
Water is another local rulebook. As of October 19, 2026, the Southwest Florida Water Management District is under Modified Phase III "Extreme" restrictions through March 31, 2027: one day per week for lawn watering, tighter hours, and local rules can be stricter (SWFWMD). If you are buying new sod or an HOA property, ask what the schedule allows.
6. Commuting across the bay is its own decision
The most expensive mistake is choosing a house for its kitchen, then discovering the commute doesn't work.
I-275 crosses the Howard Frankland Bridge between Tampa and St. Petersburg. The Gandy Bridge and Courtney Campbell Causeway are the other main crossings. The Sunshine Skyway connects southern Pinellas to Manatee County. A job in downtown Tampa plus a home in Pinellas means a bridge commute. A job in Brandon plus a home in Wesley Chapel means I-75 and I-4. Both need a rush-hour test.
FDOT opened the new southbound Howard Frankland bridge and express lanes. As of August 22, 2026, tolls are collected electronically 24/7 on the I-275 express lanes, and only passenger vehicles, registered vanpools, and buses can use them (FDOT).
Transit is bus-based. HART runs buses in Hillsborough and the TECO Line Streetcar in Tampa. PSTA runs buses in Pinellas, including the SunRunner between downtown St. Petersburg and St. Pete Beach. No train network connects the counties. Map a route first.
7. Schools are assigned by address, but "the zoned school" isn't the whole story
School assignment is address-specific and not portable across county lines.
Hillsborough County Public Schools uses attendance boundaries and also offers magnet and choice programs. For 2027–28, the choice application window runs October 21 to December 7, 2026 (HCPS). Pinellas County Schools has its own zones, magnet and fundamental programs, and a school zone locator; it updates boundaries from time to time, so an old boundary map isn't good enough. Pasco County Schools has its own assignment and choice process.
I'm not going to rank neighborhoods by school reputation. Boundaries and programs change, and the assignment that matters is attached to the exact address. Verify it for the year your child will attend, then look at programs, class sizes, transportation, and your child's needs.
8. The pre-move checklist locals wish they had
- Flood zone and evacuation zone. Insurance, building rules, and evacuation orders depend on both. Verify with the FEMA flood map and your county emergency management office.
- Insurance quotes. These set your monthly cost and your insurability. Verify with a licensed agent or the carrier.
- Property tax and homestead. Both affect escrow and taxable value. Verify with the county property appraiser.
- School assignment. Boundaries and choice programs are address-specific. Verify with the district locator.
- Rush-hour commute. Bridge and traffic reality rarely matches an off-peak drive. Drive it twice and check FDOT.
- HOA and CDD documents. Fees, rules, reserves, and assessments live here. Verify with the seller, the association, or the title company.
- Condo milestone and reserve study. Both affect assessment and financing risk. Verify with DBPR and the association.
- Utility and water rules. Deposits, irrigation limits, and storm prep vary by provider. Verify with the utility, SWFWMD, and the city or county.
- Roof, HVAC, and insurance inspection. These drive negotiation and insurability. Verify with a licensed inspector.
How this changes your mortgage plan
Most preapprovals start with price. In Tampa Bay, start with the monthly number: principal and interest, property taxes, homeowners insurance, flood insurance if required, HOA dues, CDD assessments, and cash for a hurricane deductible. Then work backward to a price.
- A lower list price in a high-risk flood zone can cost more per month than a higher list price outside it.
- Insurance can change after the address is known. A preapproval that ignores insurance is a guess.
- Condo budgets and reserve studies can affect financing and monthly cost. Review them before you remove your inspection contingency.
- If you are self-employed or have variable income, start the income documentation conversation early.
- Ask how taxes and insurance will be escrowed; a payment that fits in April may not fit in November.
This is where a local mortgage conversation helps: pressure-testing the whole monthly number before you commit. For a price range, settle your affordable monthly number before you tour. Bring the listing, insurance quote, and HOA budget for a specific address.
The bottom line
Tampa Bay rewards address-level homework. Check the flood and evacuation zones. Get insurance quotes before you fall in love. Run the tax bill, not just the list price. Drive the commute at 5 p.m. Read the HOA and condo documents. Then pick the side that fits.
The weather is a feature. The details are the price of admission.
Frequently Asked Questions
- What should I check first before moving to Tampa Bay?
- Check the exact address, not just the city. Look up the flood and evacuation zones, get insurance quotes, estimate the tax bill, confirm the school assignment, and drive the commute at rush hour. Those five items matter more than a list price.
- Is flood insurance required in Tampa Bay?
- It depends on the property and lender. Federally backed mortgages generally require flood insurance in a Special Flood Hazard Area. Outside it, a separate policy may still make sense because homeowners insurance excludes flood. Get a quote for the address.
- How much are property taxes in Tampa Bay?
- No single rate exists. Millage varies by county, city, school district, water district, and special district. Your bill can also include non-ad valorem charges like trash, stormwater, and CDD fees. Use the property appraiser's estimator, then confirm exemptions.
- Do I need a car in Tampa Bay?
- Most people do. Transit is bus-based: HART in Hillsborough, PSTA in Pinellas, the TECO Line Streetcar in Tampa, and the SunRunner in Pinellas. No rail network connects the counties. Map your route and schedule first.
- When is hurricane season in Tampa Bay?
- The Atlantic hurricane season runs June 1 through November 30. The west-central Florida rainy season runs May 25 through October 10. They overlap but are different risks. Know your evacuation zone and review your deductible.
Sources
- Tropical Cyclone Climatology (opens in a new tab)https://www.nhc.noaa.gov/climo/
- Florida Thunderstorm Season (opens in a new tab)https://www.weather.gov/tbw/rainyseason
- Evacuation Zones (opens in a new tab)https://www.tampa.gov/emergency-management/programs/evacuation-zones
- Know Your Zone, Know Your Home (opens in a new tab)https://www.floridadisaster.org/knowyourzone/
- Evacuation (opens in a new tab)https://pinellas.gov/evacuation
- Flood Map Service Center (opens in a new tab)https://msc.fema.gov/portal/home
- Buy a Flood Insurance Policy (opens in a new tab)https://www.floodsmart.gov/get-insured/buy-a-policy
- Disclosure of flood risks to prospective purchaser, Fla. Stat. § 689.302 (2025) (opens in a new tab)https://www.flsenate.gov/Laws/Statutes/2025/689.302
- Florida's Hurricane Deductible (opens in a new tab)https://www.myfloridacfo.com/division/consumers/consumerprotections/floridashurricanedeductible
- Homestead & Other Exemptions (opens in a new tab)https://www.hcpafl.org/Property-Info/Homestead-Other-Info
- Save Our Homes (opens in a new tab)https://www.hcpafl.org/Property-Info/Save-Our-Homes
- Taxing Authorities (opens in a new tab)https://www.hcpafl.org/Property-Info/Taxing-Authorities
- Property Tax Payments (opens in a new tab)https://www.hillstaxfl.gov/taxes/real-estate-tax/payment-fees/
- What Amendment 3 Means for Your Property Taxes (opens in a new tab)https://www.hillstaxfl.gov/property-tax-reform/
- I-275 (Howard Frankland Bridge) new southbound bridge between Pinellas and Hillsborough counties (opens in a new tab)https://www.fdottampabay.com/project/417/422904-2-52-01
- District Water Restrictions (opens in a new tab)https://www.swfwmd.state.fl.us/business/epermitting/water-restrictions
- Red Tide and Other Harmful Algal Blooms (opens in a new tab)https://myfwc.com/research/redtide/
- Inspections (opens in a new tab)https://condos.myfloridalicense.com/inspections
- Hillsborough Transit Authority (opens in a new tab)https://www.gohart.org/
- Pinellas Suncoast Transit Authority (opens in a new tab)https://psta.net/
- Hillsborough County Public Schools (opens in a new tab)https://www.hillsboroughschools.org/
- School Zone Locator (opens in a new tab)https://www.pcsb.org/departments/district-services/student-registration/school-zone-locator
- Pasco County Schools (opens in a new tab)https://www.pasco.k12.fl.us/
About the author
Holden Kellerhals
Mortgage Loan Originator · NEXA Lending · NMLS #2646551
Have a question about your own situation?
Creative strategies for real life. Let's make it work.